For years, many prospective homebuyers have looked at mortgage rates above 6% or 7% and thought the same thing:
I’ll wait until rates come back down.
It’s an understandable reaction.
Millions of Americans watched friends, family members and neighbors buy or refinance homes with mortgage rates near 3% during the pandemic. Compared with those numbers, a 7% mortgage can feel extraordinarily expensive.
But there is another possibility worth considering.
What if 7% isn’t a temporary interruption? What if rates near today’s levels are simply part of the housing market buyers and investors need to plan around?
As of September 24, 2026, the average 30-year fixed mortgage rate was 7.03%, according to Freddie Mac. A year earlier it was 6.30%. Freddie Mac
Nobody knows exactly where mortgage rates will be next year—or three years from now.
And that’s precisely the point.
Good housing decisions shouldn’t depend entirely on predicting them.
The 3% Mortgage Was Extraordinary
Recent history can distort our expectations.
Someone who bought or refinanced during the ultra-low-rate period may naturally think of a 3% mortgage as normal and 7% as unusually high.
A longer view tells a different story.
Mortgage rates have moved through dramatically different environments over time; Freddie Mac notes that the 30-year rate reached a record 18.63% in 1981. My Home
That doesn’t mean 7% is cheap.
It means the extraordinarily low rates buyers experienced several years ago aren’t necessarily an appropriate benchmark for deciding whether today’s rates are temporary.
For today’s buyer, the more useful question may be:
Does buying make sense for me under today’s conditions?
Interest Rates Change What a Buyer Can Afford
The difference isn’t theoretical.
Freddie Mac estimates principal and interest on a $300,000, 30-year mortgage at approximately:
$1,896 at 6.5%
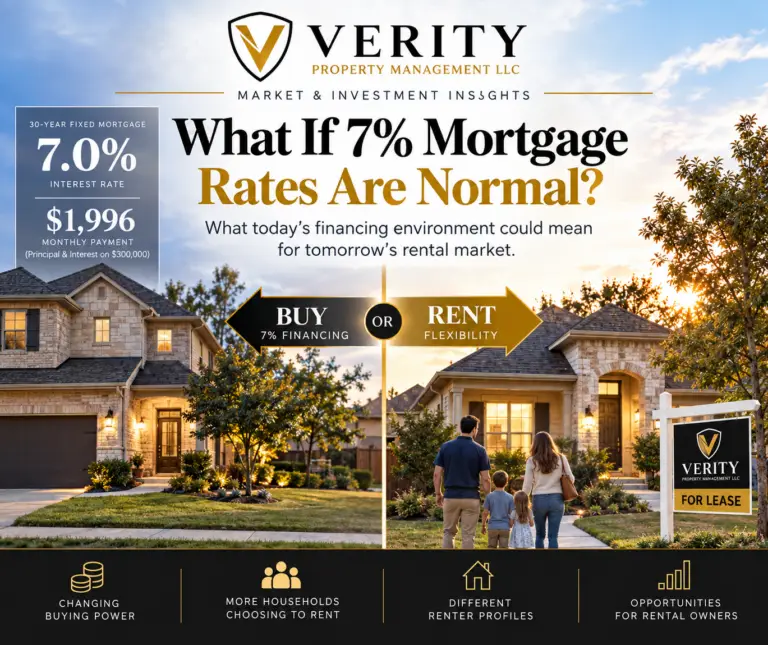
$1,996 at 7.0%
$2,098 at 7.5%
And that’s before property taxes, homeowners insurance, HOA expenses and maintenance. My Home
For a household deciding where to live, financing costs can materially change both the monthly payment and the price of the home they can comfortably afford.
That creates a difficult decision.
Buy now?
Wait?
Choose a less expensive home?
Move farther from work?
There is another option that sometimes gets overlooked.
Renting Can Be a Strategic Choice
Renting is often described as what someone does before they’re ready to buy.
That’s too simplistic.
A household may have excellent credit, a down payment and sufficient income to purchase a home—and still decide that buying doesn’t make sense under current conditions.
That household could rent the type of home it wants, perhaps even in the neighborhood where it eventually hopes to buy.
It avoids committing to today’s financing structure.
It preserves mobility.
It can continue accumulating savings.
And it retains the ability to reassess as mortgage rates, home prices, inventory and its own circumstances change.
The important point is not that mortgage rates will eventually fall.
They might.
They might not.
The value is retaining the option to make that decision later.
Renting Has Its Own Economics
None of this means renting is automatically better than buying.
Rent doesn’t build home equity.
A renter doesn’t participate directly in appreciation of the home.
Lease rates can change.
And someone who waits to buy could discover that home prices have risen even if mortgage rates eventually decline.
Buying also offers benefits that aren’t purely financial: stability, control over the property and the ability to make a home truly your own.
The right decision depends on the household.
But the assumption that renting is financially irrational whenever someone can afford to buy deserves reconsideration in a higher-rate environment.
Sometimes flexibility itself has value.
Why Rental Property Owners Should Pay Attention
This is where the conversation becomes particularly interesting for rental-property investors.
Mortgage rates don’t affect only people buying investment properties.
They also affect the people who might rent them.
When financing becomes more expensive, some households that would otherwise purchase a home may remain renters longer.
And those households aren’t necessarily traditional apartment renters.
They may be families looking for three- or four-bedroom homes.
They may want good schools, yards, garages and established neighborhoods.
They may have strong incomes and excellent credit.
What they don’t necessarily want is today’s mortgage payment.
That matters to owners of single-family rental properties.
A Changing Renter Doesn’t Mean Unlimited Rent Growth
Investors need to be careful here.
Higher mortgage rates don’t automatically mean landlords can continually increase rents.
Rental properties still compete with other rentals.
New construction affects supply.
Local employment affects demand.
Household budgets still have limits.
And every neighborhood behaves differently.
The investment question isn’t:
“Rates are high, so how much more can I charge?”
It’s:
“How are today’s housing economics changing who my potential residents are and what they value?”
That’s a market-intelligence question.
And it’s exactly the kind of question rental-property owners should be asking.
Housing Markets Are Connected
Buying and renting are sometimes discussed as though they operate in separate markets.
They don’t.
They are two ways households obtain housing.
When the economics of one change dramatically, the other is affected.
Higher mortgage rates can change purchasing power.
Home prices can change the rent-versus-buy calculation.
Apartment construction can influence rental competition.
Insurance and property taxes can affect both homeowner costs and landlord expenses.
Population and employment growth influence demand for both.
A rental-property owner who watches only rental listings is seeing just one piece of the market.
Understanding the asset requires understanding the larger housing environment around it.
Property Management Should Include Market Intelligence
Traditional property management focuses heavily on operations:
Collect the rent.
Handle maintenance.
Renew the lease.
Find the next resident.
Those functions matter enormously.
But an investment property is still an investment.
Owners should also be asking:
Who is renting in this market?
What alternatives do those renters have?
How is affordability changing?
Where is new housing supply being created?
How is the neighborhood evolving?
What could those changes mean for rent, vacancy, resident retention and the long-term value of the property?
At Verity Property Management, we believe managing a rental property well requires understanding both the home and the market around it.
We can’t predict where mortgage rates will go next.
Neither can anyone else.
But we can pay attention to what today’s rates are doing to housing decisions—and help owners think about what those changes may mean for their investment.
Because sometimes the most important question isn’t whether 7% mortgage rates will last.
It’s what happens to the rental market if they do.